This article explains public information. It does not determine eligibility or replace an official notice.
What is Asaan Karobar Finance Phase 2?
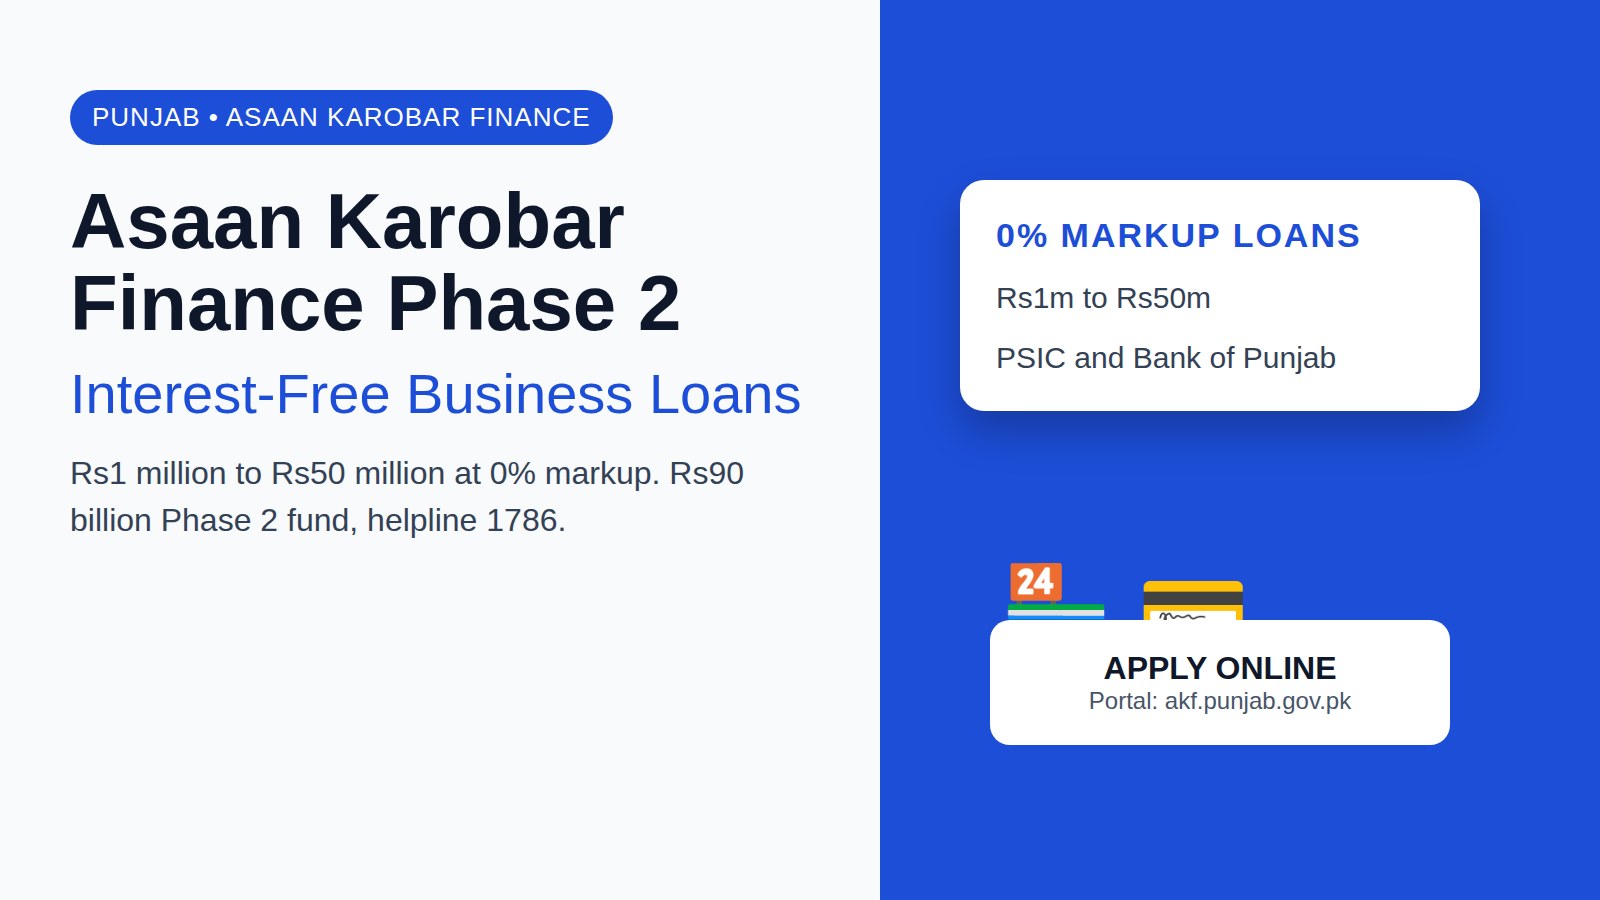
Asaan Karobar Finance Phase 2 is the next stage of the Chief Minister Punjab interest-free loan scheme for small and medium enterprises, known as SMEs. Chief Minister Maryam Nawaz Sharif launched the scheme on 16 January 2025. The Punjab Small Industries Corporation, known as PSIC, runs the scheme. The Bank of Punjab is the lender, and the Punjab Information Technology Board, known as PITB, runs the online portals.
The core idea has not changed. A Punjab business owner can borrow for a new business, for expansion, for machinery, for working capital, or for cleaner technology, and pay back only the amount borrowed. That does not mean the loan has no other costs. You still pay a processing fee, and in some cases equity, a handling fee, and insurance, legal and registration costs. Phase 2 is reported as underway, with Rs 90 billion set aside across North, Central and South Punjab, plus an export focus. A steering committee reviewed Phase 2 in August 2026. Check akf.punjab.gov.pk before you plan around a loan, as availability can change.
What changed in Phase 2?
Phase 1 is complete. In Phase 1, 4,238 people received Rs 16.31 billion, as reported in the source used for this guide.
The headline change is the size of the fund. Phase 2 carries Rs 90 billion across North, Central and South Punjab, plus an export sector focus. Eligibility and timing may differ by region or sector, so check the stream for your region. The second change is the loan ceiling. The original Finance scheme offered Rs 1 million to Rs 30 million. Phase 2 offers Rs 30 million to Rs 50 million through four special schemes. Their names and detailed terms were not published in the sources used for this guide, so this guide does not list them. The third change is the export focus. An export and SME tier offers up to Rs 50 million for exporting SMEs. Across Finance and the Card together, Rs 70 billion had been disbursed to 108,371 businesses, as reported in August 2026.
Asaan Karobar Finance vs Asaan Karobar Card: what is the difference?
Many applicants mix up the two parts of the programme. Finance is the larger term loan. The Card is the smaller card based facility. They have different portals, limits, terms, and status.
| Feature | Asaan Karobar Finance | Asaan Karobar Card |
|---|---|---|
| What it is | A term loan for SMEs | A card with a credit limit for small business spending |
| Amount | Rs 1 million to Rs 30 million, with Phase 2 and export tiers up to Rs 50 million | Up to Rs 1 million |
| Markup for the borrower | 0% | 0% |
| Term | Up to 5 years | 3 years, with a 3 month grace period |
| Repayment | Equal monthly instalments, with a grace period of 6 months for new businesses and 3 months for existing businesses | 33 monthly instalments after the grace period |
| Security | Personal guarantee for Tier 1, collateral for Tier 2 | Personal guarantee, signed digitally |
| Processing fee | Rs 5,000 for Tier 1 and Rs 10,000 for Tier 2 | Rs 500 |
| Portal | akf.punjab.gov.pk | akc.punjab.gov.pk |
| Status as of September 2026 | Finance was still showing Apply buttons | Card registration had stopped |
The Card is for small shopkeepers, home based businesses and vendors who need a smaller amount for day to day business spending. You do not get cash in hand. You get a card limit, and you spend it through digital channels such as a mobile app or a card machine. Personal spending is blocked. Finance is for businesses that need a larger lump sum for setup, expansion, machinery, working capital, commercial vehicle leasing, or climate friendly technology. Do not apply for Finance simply because the Card is closed, as Finance has stricter checks.
How much can you borrow? The tier by tier loan table
Finance has two main tiers, plus an export and SME tier. One figure is in conflict, as flagged below the table.
| Tier | Loan amount | Security | Term | Markup for borrower | Processing fee |
|---|---|---|---|---|---|
| Tier 1 | Rs 1 million to Rs 5 million | Personal guarantee | Up to 5 years | 0% | Rs 5,000 |
| Tier 2 | Rs 5 million to Rs 30 million, or Rs 6 million to Rs 30 million | Secured loan, with collateral | Up to 5 years | 0% | Rs 10,000 |
| Export and SME tier | Up to Rs 50 million | Secured loan, with collateral | Up to 5 years | 0% | Rs 10,000 |
| Phase 2 special schemes | Rs 30 million to Rs 50 million | Not published in the sources used | Not published in the sources used | 0% as reported for Phase 2 | Not published in the sources used |
Tier 1 is a clean loan with personal guarantees. You do not put up property as security, and you do not pay borrower equity, except for leased vehicles, where 25% equity applies.
Tier 2 is a secured loan. You must offer collateral, such as property papers, and you must pay 20% equity in most cases. Women, transgender persons and differently abled persons pay 10% equity instead of 20% under Tier 2. The Tier 2 starting point is in conflict. PSIC lists Tier 2 from Rs 5 million, while one report lists it from Rs 6 million. Check the live form on akf.punjab.gov.pk, and call helpline 1786 if the form and the information page disagree. Repayment is by equal monthly instalments for up to five years, with a grace period of six months for new businesses and three months for existing businesses.
Which tier fits your business? A quick decision checklist
Use this checklist before you choose a tier. Do not choose by the maximum amount alone.
- You need up to Rs 1 million, and you run a small shop or a home based business. The Card would have fitted, but its registration has stopped.
- You need Rs 1 million to Rs 5 million, you have no collateral, and you can offer personal guarantees. Tier 1 fits. Check that you are an active tax filer with a valid NTN.
- You need more than Rs 5 million, you have collateral, and you can pay 20% equity, or 10% if you qualify. Tier 2 fits.
- You export goods or services, you need up to Rs 50 million, and you have collateral. The export tier fits.
- You need Rs 30 million to Rs 50 million through a Phase 2 special scheme. Wait for PSIC to publish its names and terms.
- You cannot show clean credit, a valid NTN, or a business address in Punjab. No tier fits yet. Fix those points first, then apply.
- You need money for personal use, a wedding, or a house. No tier fits. These are business loans, and the money must be used only for the stated business purpose.
If two tiers could fit, choose the smaller one that still covers your real need. Borrow only what your business can pay back.
Who can apply for Asaan Karobar Finance Phase 2?
Eligibility for Finance is stricter than for the Card. You must be aged 25 to 55 on the date of application for Finance. The age range of 21 to 57 applies to the Card, not to Finance.
You must be a Punjab resident with a valid CNIC, as per the NADRA record, and you must have a business in Punjab. For working capital, expansion and business modernisation loans, the business premises must be owned or rented in the name of the applicant, a partner, a director, or the business. You must be an active FBR tax filer with a valid NTN, and you must have a clean credit history, checked through ECIB. A weak ECIB record or a missing NTN can stop an application, so fix those points before you pay the non refundable fee. Small enterprises are described as having annual sales up to Rs 150 million. Medium enterprises are described as having annual sales above Rs 150 million and up to Rs 800 million. For other Punjab business support, see the Prime Minister Youth Loan Scheme guide and the youth loans financing drive. Farmers should also check the CM Punjab Kisan Card and Punjab Apna Kisan Bank subsidised loans.
What documents do you need?
Keep these ready before you start. You will need a copy of your CNIC and a passport size photo, a mobile number registered in your own name, and the names, CNICs and phone numbers of two references who are not blood relatives. You will also need proof of active tax filer status, your NTN, and your business income and expense details.
For your addresses, keep a rent agreement, transfer letter or registry for your business and home address. For Tier 2, keep collateral papers such as a registry, a fard, or government securities. If you use a SIM in someone else's name, the portal can reject you. A missing premises paper is a common reason for delay, so sort it before you apply.
How to apply for Asaan Karobar Finance Phase 2 online
Apply only through the official Finance portal. If the live portal shows different steps, follow the live portal and call helpline 1786 if a step is unclear.
- Open akf.punjab.gov.pk and check that applications are open for your category. Look for the Apply button for Asaan Karobar Finance, or for the export option if you are an exporter.
- Create an account with your own mobile number. Use the number registered in your name, and keep the phone with you for the SMS code.
- Choose the right tier for the amount you need. Use the checklist above, not the largest amount on the page.
- Fill in the form with your personal, business and loan details. Set aside at least 15 minutes.
- Upload your documents, including your CNIC, photo, tax proof, address proof, and collateral papers for Tier 2.
- Pay the non refundable processing fee through the portal only. The fee is Rs 5,000 for Tier 1 and Rs 10,000 for Tier 2.
- Save the registration number shown on screen and sent by SMS. Track your status on the same portal. For help, call helpline 1786.
One report states that Finance registration was temporarily stopped when that report was written, while another source states that the Finance portal was still showing Apply buttons in September 2026. Check akf.punjab.gov.pk on the day you apply, and treat the live portal as the deciding source. If you already hold the Card, read the CM Punjab Asaan Karobar Card scheme guide for the card rules on tax registration, Urban Unit visits, and card blocking.
What does it cost? Fees, equity and charges
A 0% markup loan is not a free loan. The processing fee is Rs 5,000 for Tier 1 and Rs 10,000 for Tier 2, and it is non refundable. For the Card, the fee was Rs 500, plus a card fee of Rs 25,000 plus FED. That card fee does not apply to Finance.
For Tier 2, borrower equity is 20% in most cases, or 10% for women, transgender persons and differently abled persons. For Tier 1, equity is 0%, except for leased vehicles, where 25% equity applies. On a Rs 10 million Tier 2 loan at 20% equity, you must fund Rs 2 million yourself. Existing businesses pay a handling fee of 3% a year in the sources used here. New businesses do not pay it, and climate friendly businesses pay 0% a year. Insurance, legal and registration costs are paid by the applicant. Late payment is charged at Rs 1 per Rs 1,000 per day on the overdue amount only.
What can you use the loan for?
Finance loans can be used to start a new business, expand an existing one, buy machinery, cover working capital, lease commercial vehicles, or adopt resource efficient and climate friendly technology. The loan must be used only for the stated business purpose. If your need is a farm input loan, a livestock loan, or a job abroad loan, Finance is not the right route. Check the Punjab Rozgar Scheme guide or the CM Punjab Livestock Card instead.
Problems, delays and scams to avoid
Most delays come from four points: a weak credit or tax record, a poor business plan or missing premises papers, a wrong tier choice, and a SIM or CNIC mismatch. Fix your ECIB record and NTN before you apply, as a failed check after payment wastes the fee. If you apply for Tier 2 without collateral or equity, the application will stall. Use your own registered mobile number and a CNIC that matches the NADRA record. No loan agent is needed, and no agent can get you selected, raise your limit, or reopen registration. Never pay anyone outside the official portal. Never share an OTP, card PIN or password. If your application is delayed, track it on akf.punjab.gov.pk with your registration number, then call helpline 1786.
The separate Rs 300 billion programme: do not confuse it with Asaan Karobar
In October 2026, the Punjab Industries Minister announced a separate Rs 300 billion financing programme. It is not the same as Asaan Karobar, and it is not Phase 3. The reported structure is up to Rs 100 million interest free, Rs 100 million to Rs 1 billion at 3% markup, and Rs 1 billion to Rs 5 billion at 5% markup. No eligibility criteria, application steps or availability were published for it in the sources used here, so you cannot apply for it yet on the basis of the announcement alone. Wait for an official PSIC or Bank of Punjab notice. No official Phase 3 announcement has been made.
Frequently asked questions
What is Asaan Karobar Finance Phase 2?
Asaan Karobar Finance Phase 2 is the second phase of the Punjab interest-free business loan scheme for SMEs. It has Rs 90 billion across North, Central and South Punjab, plus an export focus, and loans of Rs 30 million to Rs 50 million through four special schemes.
How much can I borrow under Asaan Karobar Finance Phase 2?
You can borrow Rs 1 million to Rs 30 million under the original Finance tiers, and up to Rs 50 million under the export tier and the Phase 2 special schemes. Tier 1 covers Rs 1 million to Rs 5 million, and Tier 2 covers Rs 5 million to Rs 30 million on the PSIC figure.
Is Asaan Karobar Finance really interest-free?
Yes. The borrower pays 0% markup because the Punjab government pays the markup to the Bank of Punjab. You still pay a processing fee, and Tier 2 borrowers pay equity and, for existing businesses, a handling fee.
Who can apply for Asaan Karobar Finance Phase 2?
A Punjab resident aged 25 to 55 can apply with a valid CNIC, a valid NTN, active FBR filer status, a clean ECIB credit history, and a business in Punjab. The premises must be owned or rented in the name of the applicant, a partner, a director, or the business.
How do I apply for Asaan Karobar Finance Phase 2 online?
Open akf.punjab.gov.pk, create an account with your own mobile number, choose the right tier, fill in the form, upload your documents, and pay the non refundable fee through the portal only. Save the registration number sent by SMS, then track your status on the same portal.
What is the difference between Asaan Karobar Finance and Asaan Karobar Card?
Finance is a larger term loan of Rs 1 million to Rs 30 million, and up to Rs 50 million for export and Phase 2 tiers, for up to five years. The Card is a smaller facility of up to Rs 1 million for three years. Finance uses akf.punjab.gov.pk, while the Card uses akc.punjab.gov.pk, and Card registration had stopped as of September 2026.
Can I still apply for the Asaan Karobar Card?
No, not on the evidence in the sources used here. As of September 2026, the Card portal akc.punjab.gov.pk showed "registration of applications has been stopped". No reopening date had been announced. Check the live portal and call helpline 1786 first.
Do I need collateral for Asaan Karobar Finance Phase 2?
No, not for Tier 1, which needs personal guarantees only. Yes, for Tier 2 and the export tier, which are secured loans. Tier 2 also needs 20% equity in most cases, or 10% for women, transgender persons and differently abled persons.
What is the helpline number for Asaan Karobar Finance?
The official helpline is 1786. Call it for eligibility, documents, portal status, and tracking help. Finance applicants should start with 1786.
Is there a Phase 3 of Asaan Karobar Finance?
No, no official Phase 3 announcement has been made. The Rs 300 billion programme announced in October 2026 is a separate announcement, not Phase 3.
Sources and official links
Check the destination address before entering personal information.
Related guides
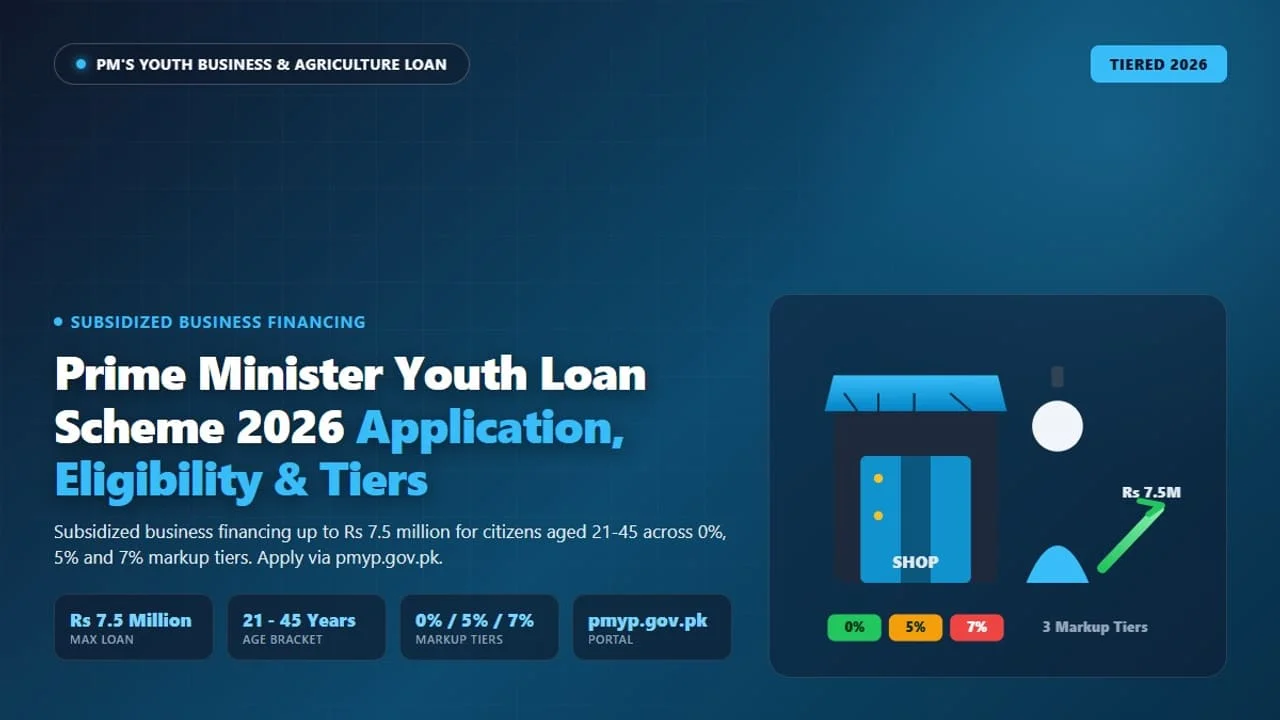
Prime Minister Youth Loan Scheme 2026: Complete Application, Eligibility & Tiers Guide
The Prime Minister Youth Loan Scheme 2026 provides subsidized business financing up to Rs 7.5 million for Pakistani citizens aged 21 to 45 across three tiers (0%, 5%, and 7% markup). Apply online through the official pmyp.gov.pk portal.
Read guide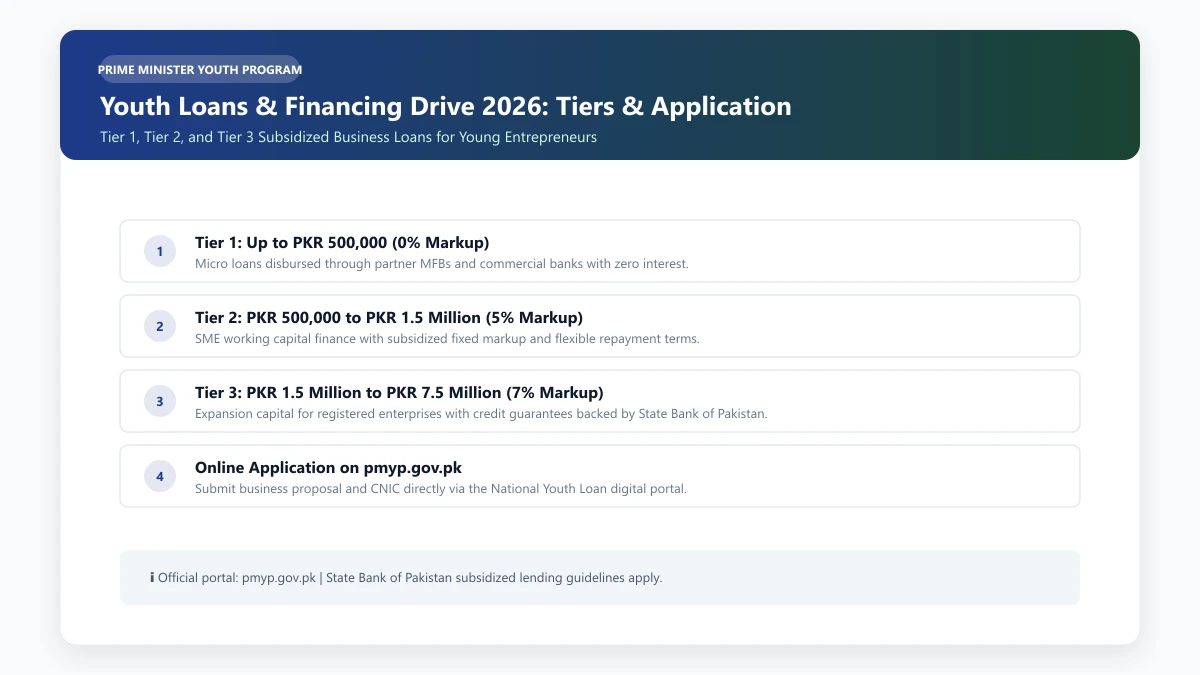
Youth Loans & Financing Drive 2026: How to Apply, Eligibility & Loan Tiers
Master the Youth Loans & Financing Drive 2026 (PMYB&ALS). Learn Tier 1–3 loan limits (up to Rs 7.5M), 0% to 7% markup rates, NADRA CNIC portal steps, and eligibility rules.
Read guide
CM Punjab Kisan Card Online Apply 2026: 8070 Registration, Eligibility & BOP Card Activation
To register for the CM Punjab Kisan Card online and via SMS in 2026, send an SMS with PKC [Space] your 13-digit CNIC to 8070 using a mobile SIM registered in your own name, or submit an application through the Punjab Agriculture Department portal (agripunjab.gov.pk). Eligible farmers holding between 1 to 12.5 acres of land receive an interest-free agricultural production loan of up to Rs. 150,000 per crop season through Bank of Punjab.
Read guide
Punjab Apna Kisan Bank: Subsidised Loans for Punjab Farmers
Punjab Apna Kisan Bank is Punjab's first specialist farm bank, announced on 28 October 2026 with Rs17 billion in subsidised agricultural loans. It is not yet open for applications in the published reports, and its loan tiers are still reported in conflict, so farmers should wait for official rules before they act.
Read guide
Ehsaas Saving Wallets Programme & Interest-Free Loans
Understand the savings-wallet initiative, how to ask about current account access, and the separate route for interest-free loans.
Read guide