This article explains public information. It does not determine eligibility or replace an official notice.
What is the Youth Loans & Financing Drive 2026 (PMYB&ALS)?
The Youth Loans & Financing Drive 2026, officially structured as the Prime Minister’s Youth Business & Agriculture Loan Scheme (PMYB&ALS), is a national financial empowerment program launched by the Government of Pakistan and regulated by the State Bank of Pakistan (SBP). The initiative provides subsidized business loans up to Rs 7.5 Million for young entrepreneurs and farmers to establish new micro-enterprises or expand existing small and medium enterprises (SMEs).
By eliminating traditional borrowing barriers, the scheme integrates young citizens into the formal banking sector across all provinces, Azad Jammu & Kashmir, and Gilgit-Baltistan. The program is executed through 15 participating commercial, Islamic, and specialized SME banks—including the Bank of Punjab (BOP), Allied Bank Limited (ABL), Habib Bank Limited (HBL), United Bank Limited (UBL), and National Bank of Pakistan (NBP).
Core Objectives and SME Financial Inclusion
The primary objective of the 2026 financing drive is to stimulate local employment, foster innovation, and increase agricultural productivity. Funds are available for both greenfield projects (brand-new business setups) and brownfield expansions (scaling operational businesses).
Borrowers can apply for term loans to acquire equipment or commercial vehicles, as well as working capital loans to purchase seasonal inventory and raw materials.
Key 2026 Policy Updates and 25% Female Quota
Under the updated 2026 policy guidelines, a mandatory 25% quota of the total loan portfolio is reserved exclusively for female entrepreneurs. Furthermore, the State Bank of Pakistan has mandated that participating banks complete application processing and credit evaluation within 45 working days from digital submission.
Who is Eligible for the Youth Loans & Financing Drive?
Eligibility for the Youth Loans & Financing Drive 2026 is determined by standardized criteria designed to ensure equitable access while maintaining credit discipline.
Age Limits for General vs. IT & E-Commerce Applicants
For general business and agricultural categories, applicants must be Pakistani citizens holding a valid CNIC aged between 21 and 45 years at the time of online application.
To encourage digital entrepreneurship, the lower age limit for IT and E-Commerce startups is relaxed to 18 years, provided the applicant holds a minimum matriculation certificate or technical diploma. For corporate entities or partnerships, at least one director or partner representing the majority stake must fall within the designated age bracket.
Citizenship, Employment Restrictions, and eCIB Standards
All applicants must possess an unexpired CNIC issued by NADRA and maintain a clean credit history free of bank loan defaults (verified via the electronic Credit Information Bureau - eCIB). Public sector employees working in federal, provincial, or semi-government institutions are strictly ineligible for loan distribution under this program.
What Are the Three Loan Tiers and Markup Rates?
The Youth Loans & Financing Drive categorizes loan amounts into three structured tiers based on capital size, interest markup subsidy, and security requirements.
Tier 1 Loan: Up to Rs. 500,000 (0% Markup / Interest-Free)
Tier 1 provides micro-financing up to Rs. 500,000 at a 0% annual markup rate, functioning as a completely interest-free credit facility. Borrowers do not need to pledge land or physical property; the loan is sanctioned against a single personal guarantee of a reputable third party holding a valid CNIC.
Tier 2 Loan: Rs. 500,000 to Rs. 1.5 Million (5% Subsidized Markup)
Tier 2 caters to small enterprise expansion with loan limits ranging from Rs. 500,000 up to Rs. 1,500,000 at a concessional 5% annual markup. Similar to Tier 1, Tier 2 financing relies on personal guarantees rather than property mortgages, significantly lowering security hurdles for young founders.
Tier 3 Loan: Rs. 1.5 Million to Rs. 7.5 Million (7% Subsidized Markup)
Tier 3 supports medium-scale industrial, commercial, and agricultural projects, granting credit from Rs. 1.5 Million up to Rs. 7.5 Million at a 7% annual markup. Due to higher financial exposure, Tier 3 loans require collateral security—such as property hypothecation, commercial vehicle registration, or agricultural land passbooks—as mandated by the selected executing bank’s credit policy.
| Loan Tier | Maximum Amount | Annual Markup Rate | Security / Collateral Requirement | Maximum Repayment Tenor |
|---|---|---|---|---|
| Tier 1 (T1) | Up to Rs. 500,000 | 0% (Interest-Free) | Single Third-Party Personal Guarantee | Up to 8 Years (1-Yr Grace Period) |
| Tier 2 (T2) | Above Rs. 500,000 to Rs. 1.5 Million | 5% Subsidized | Single Third-Party Personal Guarantee | Up to 8 Years (1-Yr Grace Period) |
| Tier 3 (T3) | Above Rs. 1.5 Million to Rs. 7.5 Million | 7% Subsidized | Bank Credit Policy / Asset Mortgage | Up to 8 Years (1-Yr Grace Period) |
How to Apply Online for Youth Loans Step-by-Step
All applications for the Youth Loans & Financing Drive 2026 must be submitted online through the official portal at pmybals.pmyp.gov.pk. Physical paper forms submitted at bank branches are not accepted.
Step 1: CNIC Registration & NADRA Verification
Visit pmybals.pmyp.gov.pk and click on New Applicant Form. Enter your full name, 13-digit CNIC number, CNIC issuance date, and mobile number. The system performs real-time identity validation via NADRA.
Important Troubleshooting Note: Ensure the mobile SIM card used during registration is registered directly under your own CNIC. Mismatched SIM ownership will cause OTP verification failures.
Step 2: Selecting Participating Bank and Loan Category
Choose your preferred executing bank from the drop-down menu (e.g., Bank of Punjab, Allied Bank, HBL, UBL, or ZTBL). Select your business category (Business or Agriculture) and pick your target loan tier (Tier 1, Tier 2, or Tier 3).
Step 3: Submitting Feasibility Report & Financial Statements
Fill out the digital business plan section. For new startups, input estimated startup costs, monthly revenue projections, and operational expense breakdowns. For existing businesses, attach financial statements or bank transaction records for the preceding 12 months. Review all fields and submit your application to generate a unique tracking reference number.
What Documents Are Required for the Youth Financing Drive?
Preparing required digital documents beforehand prevents application rejection and speeds up processing time.
- Valid CNIC Scans: High-resolution front and back color scans of the applicant's CNIC.
- Passport Photograph: Recent digital photo with blue or white background.
- Educational / Skill Certificates: Matriculation, intermediate, degree, or technical vocational certificates (mandatory for IT category).
- Business Feasibility Plan: Basic project description detailing income sources, machinery costs, and location details.
- Guarantor Credentials: CNIC copy and contact details of the third-party guarantor for Tier 1 and Tier 2 loans.
- Property / Security Papers: Title deeds or land passbook scans (required only for Tier 3 applicants).
- Existing Business Proof: Shop lease agreement, utility bill scan, or NTN/ATL tax registration (if applying for business expansion).
How to Track Your PM Youth Loan Application Status Online
Applicants can monitor the real-time processing status of their loan request directly on the portal without visiting bank branches.
- Navigate to pmybals.pmyp.gov.pk/pmyphome/TrackApplication.
- Enter your 13-digit CNIC number without dashes.
- Type your registered mobile number and click Track Application.
- Submitted / Under Review: Application received and awaiting initial bank screening.
- Assigned to Executing Bank: Assigned to your chosen bank branch for credit assessment.
- Verification / Field Survey: Bank official visiting business premises or conducting guarantor check.
- Sanctioned / Approved: Loan approved; visit branch for final agreement signing and disbursement.
Loan Repayment Tenors, Grace Periods, and Bank Guidelines
Understanding repayment terms helps borrowers manage business cash flow effectively and avoid penalty charges.
Development Loans vs. Working Capital Financing Terms
Long-Term Development Loans: Designed for purchasing machinery, constructing business premises, or acquiring commercial vehicles. The maximum repayment tenor is 8 years, which includes a 1-year grace period where principal repayment is deferred.
Working Capital Loans: Designed for inventory purchases, raw materials, and daily operational overheads. The maximum repayment tenor is 5 years, offering flexible quarterly or monthly repayment structures aligned with business revenue cycles.
Frequently asked questions
Is Tier 1 of the PM Youth Loan completely interest-free?
Yes, Tier 1 financing up to Rs. 500,000 carries a 0% annual markup rate, functioning as a completely interest-free loan facility sponsored by the government subsidy.
Can female applicants apply for all three loan tiers?
Yes, female applicants can apply across Tier 1, Tier 2, and Tier 3. Additionally, a dedicated 25% quota of the overall loan fund is reserved specifically for female entrepreneurs.
What is the age limit for IT sector applicants in 2026?
Applicants launching IT or E-Commerce ventures are eligible from age 18 up to 45 years, provided they hold a minimum matriculation certificate or vocational IT diploma.
Is physical land collateral required for Tier 2 youth loans?
No, Tier 2 loans (Rs. 500,000 to Rs. 1.5 Million) do not require property or land collateral. They are issued against a single third-party personal guarantee.
Can existing business owners apply for loan expansion?
Yes, existing small and medium business owners can apply under brownfield expansion to upgrade machinery, increase stock, or expand commercial facilities.
Are government employees eligible for PM Youth Loans?
No, employees working in government departments, public sector entities, or autonomous state institutions are ineligible for financing under this scheme.
How long does it take for a bank to process the loan application?
Standard portal guidelines mandate that participating executing banks complete verification and credit evaluation within 45 working days from submission.
What should I do if my SIM card is registered under another person's CNIC?
You must register a mobile SIM card under your own CNIC before applying. The portal uses NADRA automated cross-matching and will block applications with mismatched SIM ownership.
Can I choose any participating bank for my loan processing?
Yes, applicants can select any listed commercial or Islamic bank (such as BOP, ABL, HBL, UBL, or NBP) from the portal drop-down menu based on personal preference or proximity.
What is the grace period for repayment on long-term development loans?
Long-term development loans include a maximum grace period of up to 1 year, during which the borrower is exempt from paying the principal loan installment.
What minimum educational qualification is required for general business loans?
There is no minimum educational requirement for general business or agricultural loans. Educational documents are only mandatory for IT and specialized technical categories.
How can I correct an error in my submitted online application?
Once submitted, an online application cannot be edited directly on the portal. You must visit the designated branch of your chosen executing bank with original documents to request corrections before credit sanctioning.
Sources and official links
Check the destination address before entering personal information.
Muhammad Salman specializes in Pakistani public sector financing, youth entrepreneurship schemes, and government subsidy programmes, cross-referencing all data against official SBP circulars and ministry directives.
Ayesha reviews programme-eligibility and payment content for accuracy against BISP, NADRA NSER, and provincial notices, and flags any guide that needs an update after an official policy change.
Related guides
Major Government Schemes Updates (September/October 2026): Key Policy Changes, New Funds & Beneficiary Guidelines
Discover major government scheme updates for September/October 2026, including the ₹10,000 Cr SME Growth Fund, Ayushman Bharat 70+ Vay Vandana Card, BHAVYA Rasayan guidelines, PM-Kisan & PM Surya Ghar.
Read guide
Other Active Financial Support: Complete Grant Disclosure & Compliance Guide
Other active financial support refers to all financial, physical, and personnel resources—whether domestic or foreign, direct cash grants, in-kind contributions, or outside consulting—currently available to research personnel. Federal agencies like NIH and NSF require full disclosure of active support to prevent scientific overlap, double-budgeting, and effort overcommitment.
Read guide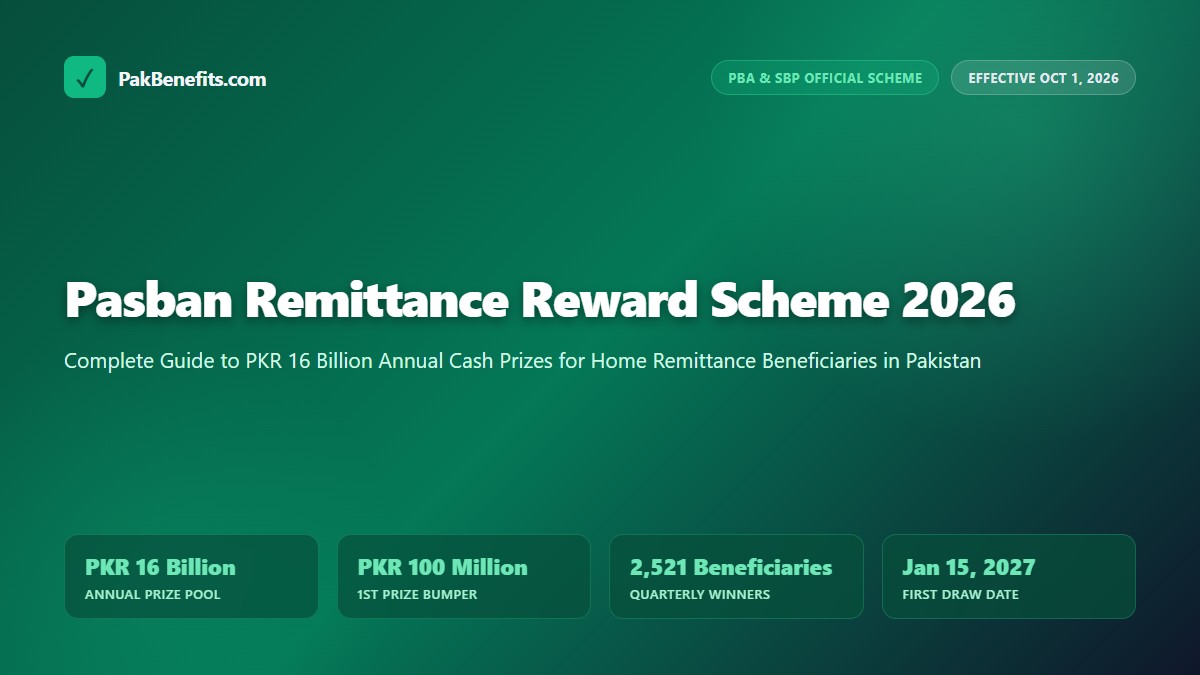
Pasban Remittance Reward Scheme 2026: Eligibility, PKR 16B Prizes & Draw Guide
Complete guide to the Pasban Remittance Reward Scheme (PRRS) launched by PBA & SBP. Learn eligibility requirements, USD 100 monthly threshold, PKR 16 Billion annual cash prize tiers, 1LINK token draws, and official winner check portals.
Read guide
Provincial & Regional Schemes: Complete List, Eligibility & Application Guide (2026)
Discover all 2026 Provincial & Regional Schemes across Punjab, Sindh, KP, and Balochistan. Learn eligibility rules, PSER CNIC online verification, and application steps.
Read guide
Public Sector Development Programme (PSDP) 2026–27: Comprehensive Budget Allocation & Project Breakdown
Discover the Public Sector Development Programme (PSDP) 2026–27 outlay of Rs 3,675 billion, including Rs 1,000 billion for Federal PSDP, provincial ADPs, NHA and Water sector allocations, 5Es strategy, and Q1 fund release updates.
Read guide