This article explains public information. It does not determine eligibility or replace an official notice.
What is the Asaan Karobar Card?
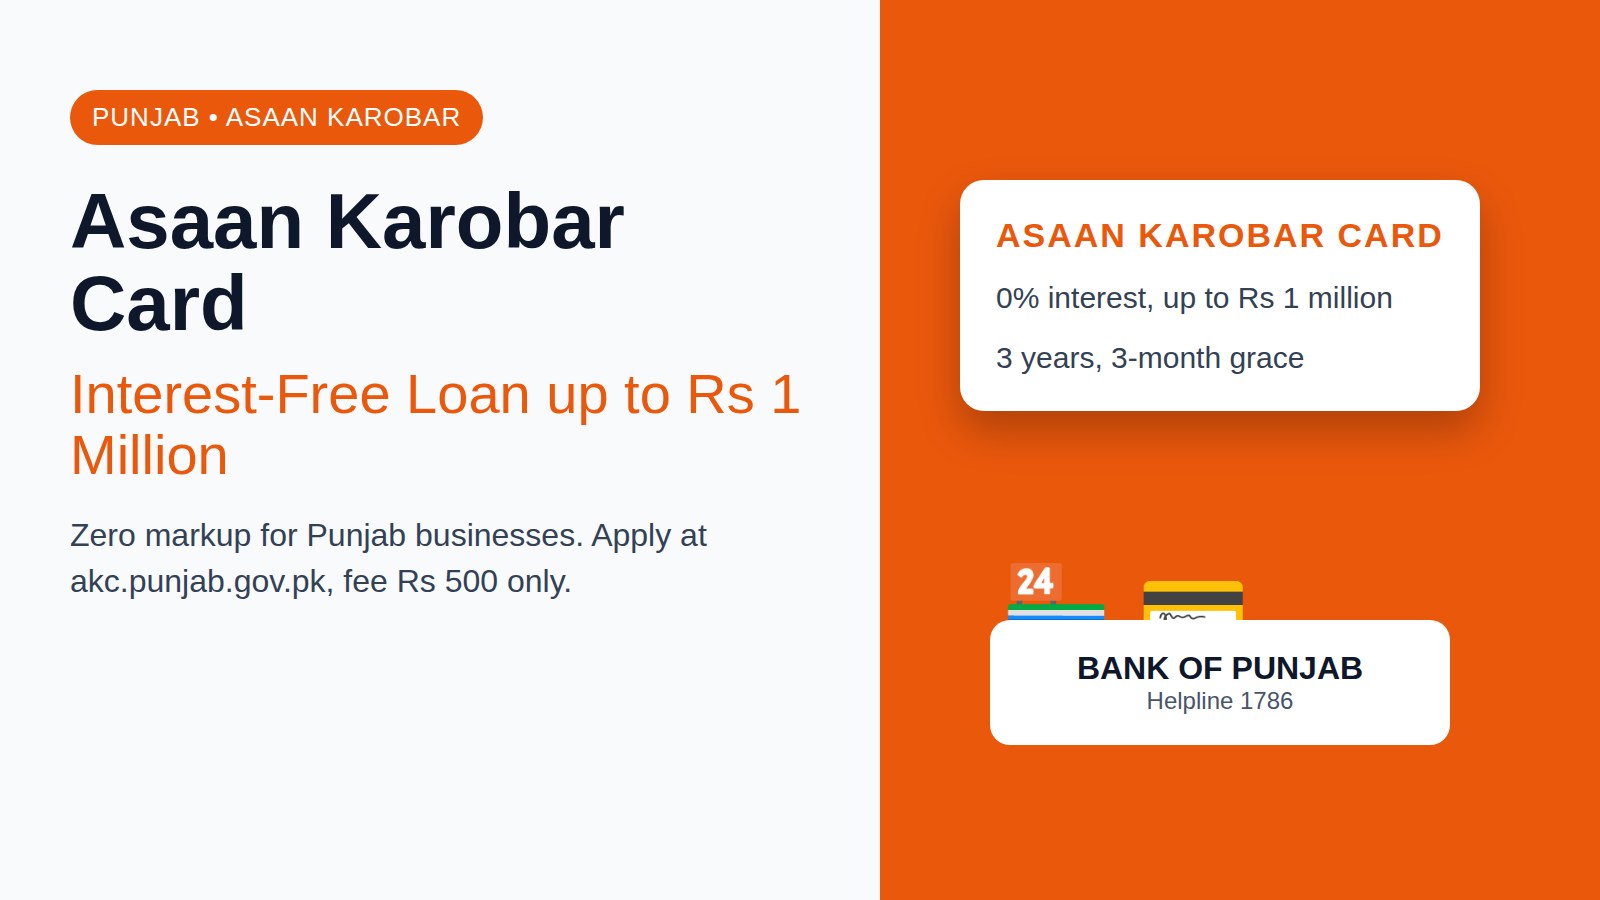
The Asaan Karobar Card is a digital SME card from the Government of Punjab. It works like a business credit card, not a cash loan. You get a credit limit for business spending, and you repay what you use in monthly instalments.
The Government of Punjab launched the scheme on 16 January 2025 under Chief Minister Maryam Nawaz Sharif. The Punjab cabinet had approved it two days earlier. The Punjab Small Industries Corporation (PSIC) owns the scheme, the Punjab Information Technology Board (PITB) manages the portal at akc.punjab.gov.pk, and the Bank of Punjab is the lender. It targets small shopkeepers, traders, startups, and skilled workers. It is a business loan, not a BISP cash transfer.
How the card is different from a normal bank loan
A normal bank loan charges markup from day one and often needs collateral. The Asaan Karobar Card charges the borrower 0% interest because the Punjab government pays the markup to the Bank of Punjab. The card needs no collateral. You give a personal guarantee instead, which you sign digitally.
Can you apply for the Asaan Karobar Card right now?
Check the official portal before you apply. As of September 2026, two guides report it showed "Registration of applications has been stopped." A third guide found the same message on 3 October 2026. No new round has been announced.
One other guide says applications are open now and no fixed closing date has been announced. These reports conflict, so do not trust a social media post that claims a new round is open. If the official portal does not show it, it is not open. Call 1786 to confirm. Asaan Karobar Finance may still be open at akf.punjab.gov.pk.
What changed since the launch
The Punjab cabinet approved the scheme on 14 January 2025, and applications opened on 16 January 2025. By December 2025, a government press release said 104,131 cards had been issued, with Rs 44 billion in card-based loans. As reported, the combined schemes supported 108,371 businesses with Rs 70 billion disbursed in six months. These are reported government figures, not checked directly against a punjab.gov.pk release. In September 2026, the card portal started showing that new registrations had stopped, while Finance moved into Phase II.
How much can you borrow through the Asaan Karobar Card?
The Asaan Karobar Card gives an interest-free loan from Rs 100,000 to Rs 1 million, repaid over three years after a three-month grace period. It is the first tier of a three-tier scheme. The larger tiers are term loans with a subsidised markup, not 0% interest. There is also an export finance variant of up to Rs 50 million for exporting SMEs.
| Tier | Loan range | Interest for the borrower | Who it suits |
|---|---|---|---|
| SME Card (Tier 1) | Rs 100,000 to Rs 1 million | 0%, fully interest-free | Startups, small shopkeepers, skilled youth |
| Asaan Karobar Finance (Tier 2) | Rs 1 million to Rs 5 million | Subsidised markup | Growing small businesses |
| Asaan Karobar Finance (Tier 3) | Rs 5 million to Rs 3 crore | Low markup, 6-month KIBOR + 2.40% | Established SMEs |
The government pays the bank's full commercial rate, 6-month KIBOR plus 2.40%, for the SME Card, so your rate is 0%. For Tier 2 and Tier 3, the subsidy covers only part of that rate.
Asaan Karobar Card vs Asaan Karobar Finance
The card is a revolving credit limit for daily business spending. It needs no collateral and no business plan, and it suits small traders who need quick access to working capital. Asaan Karobar Finance is a term loan for bigger amounts. It needs a business plan, and the larger tiers need security such as a property mortgage. Do not confuse the card with the Parwaz Card, which funds pre-departure costs for a confirmed overseas job, or the federal PM Youth Loan, which covers all of Pakistan.
Who can apply for the Asaan Karobar Card?
You must be a Pakistani national aged 21 to 57, living in Punjab, with a business in Punjab too. It can be an existing business or one you plan to start. You need a valid NADRA CNIC that has not expired, and a mobile number registered in your own name.
You must have a clean credit history, with no unpaid or defaulted loans. The Bank of Punjab runs a credit check and a psychometric assessment as part of the decision. You do not need to be a tax filer to apply, but you must register with the Federal Board of Revenue (FBR) or the Punjab Revenue Authority (PRA) within six months of getting the card. Only one application is allowed per person and per business. The scheme does not need PSER registration. Unlike the Rashan, Himmat, and Kisan Cards, which run through the PSER poverty database, Asaan Karobar is credit-based.
What documents do you need?
Keep these documents ready before you start the online form. Blurry uploads are a common reason for rejection.
- Valid CNIC copy, front and back.
- Bank statement for the last six months.
- Business proof, such as a rental agreement or ownership papers in your name.
- NTN certificate, if you have one.
- Business plan, only for Tier 2 and Tier 3 Finance loans.
- Mobile number registered under your own CNIC.
- Rs 500 processing fee receipt.
Upload each file as a clear JPG or PDF.
How do you apply for the Asaan Karobar Card online?
The process is fully digital. Follow these steps when registration is open.
- Go to akc.punjab.gov.pk only. Do not pay any agent.
- Register with your name, parent's name, date of birth, and CNIC.
- Add your own-name mobile number, create a password, and click Register.
- Log in with your CNIC and password to reach your dashboard.
- Fill in your personal details.
- Add your business details.
- Enter your loan details. Pick the amount and tier that matches your need.
- Upload your documents, then submit and pay the Rs 500 processing fee.
The Bank of Punjab then verifies your details and runs a psychometric assessment. This typically takes 4 to 6 weeks. After approval, the card is issued and you activate it with a PIN.
How do you check your Asaan Karobar Card status by CNIC?
Log in at akc.punjab.gov.pk with your CNIC and password, then open "Application Status" on your dashboard. Pending means under review, typically 4 to 6 weeks. Approved means the loan is approved. Rejected shows the reason. Requires Documents means a file is missing or unreadable, so re-upload it.
If approval takes longer than six weeks, check for a "Requires Documents" notice first, then call 1786 with your CNIC and application date.
How does repayment work?
The SME Card gives a three-month grace period, then you pay a minimum of 5% of the remaining principal each month during the first year. Only half of your approved limit is released in the first six months. The second half comes only after you register with the FBR or PRA and show proper use of the first half. After the first year, the balance is repaid in 24 equal monthly instalments over two years. The full term is three years.
The Bank of Punjab also caps repayments at 40% of net income for Tier 1 and 50% for Tier 2. This is the debt burden ratio. If you already hold a card, note this. The card will be blocked after six months unless you have a positive verification report from the Urban Unit and you are registered with the PRA or FBR.
What does the Asaan Karobar Card cost?
The loan itself is interest-free, but the card is not free.
| Charge | Amount |
|---|---|
| Processing fee (one-time) | Rs 500, non-refundable |
| Annual card fee | Rs 25,000 + FED, deducted from your approved limit |
| Late payment charge | Rs 1 per Rs 1,000 per day overdue |
| Handling fee, new (greenfield) business | 0%, free |
| Handling fee, existing (brownfield) business | 3% per annum |
Pay the processing fee on the portal itself. The annual card fee comes out of your approved limit. Late payments are charged daily, so paying on time matters. You must still repay every rupee you use.
For the larger Finance tiers, Tier 1 needs only a personal guarantee. Tier 2 needs a property mortgage and 20% equity, or 10% for women and persons with disabilities.
What can you use the card for, and what is blocked?
Use the card only for verified business expenses: supplier and vendor payments, utility bills, government fees, and taxes. You can also buy through shop card machines and the mobile app. Cash withdrawal is capped at 25% of your limit, through ATMs only.
Personal spending is blocked. You cannot use the card for entertainment, personal shopping, or any expense that is not tied to your business. The card is a revolving credit limit for the first 12 months. After that, the balance moves into the fixed instalment plan.
Why do Asaan Karobar Card applications get rejected?
Incomplete or unclear documents are the top cause of rejection. A missing CNIC copy, a missing business proof, or a blurry upload can stop your application at once. Re-scan your documents in good light and upload them as PDF where possible. Wrong or fake information leads to instant rejection. The system cross-checks your CNIC, SIM ownership, and credit record, so any mismatch is caught fast.
A mobile number not registered under your own CNIC is another common failure. If the SIM belongs to a spouse, parent, or sibling, transfer it into your own name at a telecom service centre before you apply. A poor or unpaid credit history can trigger automatic rejection, so clear outstanding balances first. A weak or missing business plan hurts Tier 2 and Tier 3 applications, so state clearly what the business does, who it sells to, and how the loan will be used.
No FBR or PRA tax registration can also slow or block approval, so complete it early. If you are rejected, log in to akc.punjab.gov.pk and read the specific reason on your dashboard. Fix only the flagged issue. There is no cooling-off period, so you can submit a fresh application once the problem is resolved.
How do you stay safe from scams?
The only official payment is the Rs 500 processing fee, paid on the portal through the PSID it gives you. No agent can get you selected, raise your limit, or reopen registration.
Never share your OTP, card PIN, or password with anyone. The digital signing codes are for you alone. Use only akc.punjab.gov.pk for the card and akf.punjab.gov.pk for Finance, and deal only with verified Bank of Punjab staff. If someone asks you for money to guarantee approval, it is a scam. Report the contact to 1786 and do not share your CNIC or banking details.
Frequently asked questions
What is the Asaan Karobar Card?
It is a Punjab government digital card that gives small business owners an interest-free loan of up to Rs 1 million. The Bank of Punjab issues the card, PITB manages the portal, and the Punjab government pays the markup so the borrower pays 0% interest.
Can I apply for the Asaan Karobar Card right now?
Check the official portal first. As of September and October 2026, three guides report that akc.punjab.gov.pk showed "Registration of applications has been stopped," while one guide says applications are open. Call 1786 to confirm.
How much loan does the Asaan Karobar Card give?
The card gives an interest-free loan from Rs 100,000 to Rs 1 million, repaid over three years after a three-month grace period. Larger loans come through Asaan Karobar Finance.
Who is eligible for the Asaan Karobar Card?
You must be a Pakistani national aged 21 to 57, living in Punjab, with a valid NADRA CNIC and a mobile number in your own name. Your business, existing or planned, must be in Punjab, and you need a clean credit history plus a credit and psychometric assessment.
Do I need collateral for the Asaan Karobar Card?
No. Tier 1 works on a personal guarantee that you sign digitally. Collateral is only needed for the larger Finance tiers above certain amounts.
Is the Asaan Karobar Card really interest-free?
Yes, the borrower pays 0% interest because the Punjab government pays the markup to the Bank of Punjab. But it is not free. You pay a Rs 500 processing fee, a Rs 25,000 plus FED annual card fee comes out of your limit, and late payments are charged.
Do I need PSER registration to apply?
No. Approval depends on your credit history, business documents, and a psychometric assessment. A PSER poverty score plays no part, unlike the Rashan Card, Himmat Card, and Kisan Card.
What documents do I need to apply?
You need a valid CNIC copy, a bank statement for the last six months, business proof such as a rental agreement or ownership papers, and a mobile number in your own name. You also need an NTN certificate if you have one, and a business plan only for Tier 2 or Tier 3 Finance loans.
How do I check my Asaan Karobar Card status by CNIC?
Visit akc.punjab.gov.pk and log in with your CNIC number and password. Open your dashboard and click "Application Status." It will show Pending, Approved, Rejected, or Requires Documents, with the reason shown for a rejected or incomplete case.
What happens if I do not register for tax within six months?
Your card can be blocked. The second half of your limit is released only after you register with the FBR or PRA and show proper use of the first half. The card is also blocked after six months without a positive Urban Unit report and tax registration. *Disclaimer: Terms can change. Verify the current terms on akc.punjab.gov.pk or by calling 1786 before you apply, and never pay any agent who claims to guarantee approval.*
Sources and official links
Check the destination address before entering personal information.
Related guides
Punjab One Million Youth Skills Plan: Mahir, Global Rozgar, Advance Tech and Language Learning Explained
Punjab plans to train one million young people in technical and vocational skills over three years. The target was announced on 1 November 2026, and it covers industrial training, business process outsourcing, emerging technology, agriculture, and language learning. It is a target, not an open application form.
Read guide
PM Youth Business & Agriculture Loan: Before You Apply
Review the official eligibility rules, application route, and documents before starting.
Read guide
Prime Minister Youth Loan Scheme 2026: Complete Application, Eligibility & Tiers Guide
The Prime Minister Youth Loan Scheme 2026 provides subsidized business financing up to Rs 7.5 million for Pakistani citizens aged 21 to 45 across three tiers (0%, 5%, and 7% markup). Apply online through the official pmyp.gov.pk portal.
Read guide
Punjab Apna Kisan Bank: Subsidised Loans for Punjab Farmers
Punjab Apna Kisan Bank is Punjab's first specialist farm bank, announced on 28 October 2026 with Rs17 billion in subsidised agricultural loans. It is not yet open for applications in the published reports, and its loan tiers are still reported in conflict, so farmers should wait for official rules before they act.
Read guide
CM Punjab Kisan Card Online Apply 2026: 8070 Registration, Eligibility & BOP Card Activation
To register for the CM Punjab Kisan Card online and via SMS in 2026, send an SMS with PKC [Space] your 13-digit CNIC to 8070 using a mobile SIM registered in your own name, or submit an application through the Punjab Agriculture Department portal (agripunjab.gov.pk). Eligible farmers holding between 1 to 12.5 acres of land receive an interest-free agricultural production loan of up to Rs. 150,000 per crop season through Bank of Punjab.
Read guide