This article explains public information. It does not determine eligibility or replace an official notice.
What is the Ehsaas Naujawan Programme?
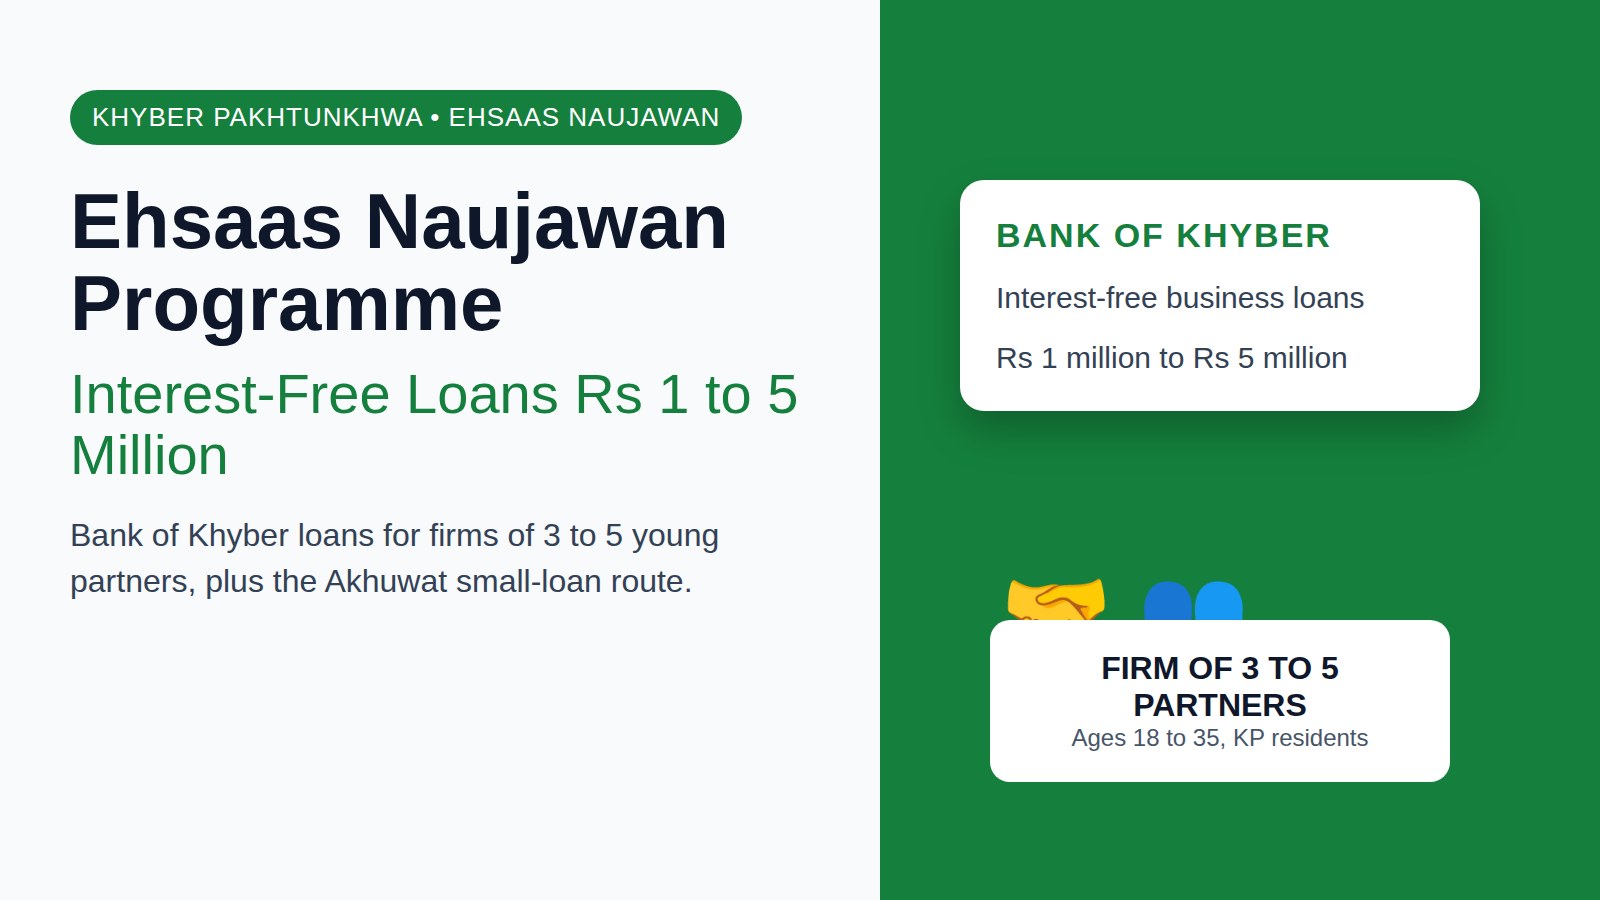
The Ehsaas Naujawan Programme is a youth business loan scheme run by the Government of Khyber Pakhtunkhwa. It gives interest-free loans to young people who want to start or grow a business. The province runs it through two partners: the Bank of Khyber for larger loans and Akhuwat Islamic Microfinance for smaller ones.
The idea is simple. A young person with a workable business plan should not be shut out of finance just because they cannot pay interest. Both routes charge no mark-up, so you repay only what you borrowed.
How much can you borrow?
You can borrow between Rs 100,000 and Rs 5 million under the programme. The amount depends on which partner you apply through. The Bank of Khyber route is for a registered firm, while the Akhuwat route is for a single borrower at a branch. The Bank of Khyber calls its loan a term loan, or demand finance.
| Bank of Khyber | Akhuwat Islamic Microfinance | |
|---|---|---|
| Loan size | Rs 1 million to Rs 5 million per firm | Rs 100,000 to Rs 500,000 per borrower |
| Mark-up | None, no service charge | None, 0% |
| Who applies | A registered firm of 3 to 5 partners | A single young borrower |
| Tenure | Up to 8 years | 36 to 60 months, confirm your exact term with your branch |
| Grace period | Up to 20 months | Check with your branch |
| Security | Personal guarantee of all partners plus a corporate guarantee of the firm | Social guarantee, a guarantor, no property needed |
| How to apply | Online at ehsaasnaujawan.bok.com.pk | At your nearest Akhuwat branch |
Pick the route before you gather papers. The two routes ask for different documents, different partners, and different security. If you need more than Rs 500,000, only the Bank of Khyber route can help. If you work alone and need less, Akhuwat is the route to take.
Who can apply for the Bank of Khyber loan?
The Bank of Khyber loan is for a group, not a single person. You must form a registered firm, company, or partnership of 3 to 5 partners. Every partner must meet the rules. If one partner fails a rule, the whole firm fails it.
Every partner must be a permanent resident of Khyber Pakhtunkhwa, including the merged districts, and hold a valid CNIC. Every partner must be aged 18 to 35. The firm must be a legal entity based in Khyber Pakhtunkhwa, either a potential start-up or an existing business less than two years old with growth potential.
The business idea must be workable, tied to the partners' skills, and backed by a business plan the bank can verify. The business must be able to create more jobs. A clean e-CIB record is required. An old loan that was repaid on time is acceptable, as long as the new debt does not push the burden past the bank's limit.
Women entrepreneurs are encouraged to apply. Graduates and skilled people with a clear plan are the named target. Siblings can be partners together, provided each one meets the criteria on their own.
Who cannot apply?
The Bank of Khyber page lists who is shut out, and the list is strict. Anyone applying alone is out. The scheme does not lend to individuals, and the bank's FAQ answers that question with a plain no.
A loan defaulter cannot apply. Anyone with a loan from a government or donor scheme or a bank that is more than 60 days overdue is also out. Employees of any government, semi-government, or autonomous body cannot apply, and the FAQ repeats this rule. Bank of Khyber staff and consultants engaged on the scheme are excluded too.
Some trades are shut out as well. Businesses on the Government of Pakistan's negative list will not be encouraged. The page names arms and ammunition, explosives, radioactive substances, security printing, and alcoholic beverages and liquor.
One more limit applies. One firm gets one loan. If your partners already hold an Ehsaas Naujawan loan through another entity, check with the bank before you apply again, because the FAQ says one entity can take only one loan.
Which businesses qualify?
Any legal business qualifies, but the bank names some sectors first. The target sectors are broad: all sectors, with a special focus on IT, services, retail trading, manufacturing, businesses in enterprise clusters, and start-ups.
The page then lists examples it wants to see. They include education, technology and AI, healthcare and biotechnology, tourism, hotels and restaurants, and green energy. It also covers any other skill-based micro and small-scale enterprising idea, or an existing business with a viable future.
A team of professionals assesses each idea, according to the FAQ. The State Bank's small enterprise definition applies, so the plan should match that scale.
The test is not the sector name on your form. It is whether the plan is verifiable, tied to the partners' skills, and able to create jobs. A software team with a real client contract fits. Three friends who each want their own separate shop do not make a firm, and the scheme is not built for them.
How do you apply for the Bank of Khyber loan?
Applications go through the designated web portal, which the bank links as ehsaasnaujawan.bok.com.pk. The FAQ gives no paper route. Form the partnership or company before you start, because the portal asks for the entity, not just the people.
- Pick 3 to 5 partners, all aged 18 to 35 with KP CNICs and clean credit histories.
- Register the firm, partnership, or company so it is a legal entity based in Khyber Pakhtunkhwa.
- Write a business plan that the bank can verify, with the 10 per cent equity shown as cash or existing assets.
- Open the portal at ehsaasnaujawan.bok.com.pk and submit the application with the partners' details.
- Wait for the bank's assessment. Disbursement comes in tranches once the formalities are complete.
Our source could not open the portal itself, so its form fields are not described here. Expect it to ask for the partners' CNICs, the registration papers, and the plan.
Repayment is in equal monthly instalments, or EMI, after the grace period. The bank has published no processing time, so this guide cannot tell you how many weeks the assessment takes.
How do you apply for the smaller Akhuwat loan?
The Akhuwat loan works differently. You apply at a branch, not online. Go to your nearest Akhuwat branch in Khyber Pakhtunkhwa and fill in the Ehsaas Naujawan loan form there. The branch list is on the official Akhuwat site, akhuwat.org.pk.
You will need your valid CNIC, a passport-size photograph, your guarantor's CNIC, and a utility bill if you have one. The branch may ask for other documents, so take what you have and ask what is missing before you leave.
The branch checks your business idea, your household situation, and your ability to repay. It also verifies your guarantor, because the loan runs on a social guarantee instead of property. Under the programme's PC-I, applicants must be permanent KP residents with a valid CNIC, aged 18 to 35, able to run a business, not blacklisted by NACTA, and not a defaulter of any financial institution. A Credit Information Report is used for the defaulter check.
Akhuwat loans can be used for working capital, raw material, machinery or equipment, a new business, or expanding an existing one. Loans of Rs 100,000 or more are transferred only to a bank account, so keep your account details ready.
The programme aims to give at least 15 per cent of its loans to women.
How does repayment work?
Repayment starts after the grace period, in equal monthly instalments. For the Bank of Khyber loan, the tenure runs up to 8 years with a grace period of up to 20 months.
Disbursement comes in tranches, after the required formalities are completed. The bank does not hand over the full amount at once. It releases the money in stages as the business meets the agreed steps.
The 90:10 debt-to-equity ratio sets the shape of the loan. The bank funds 90 per cent of the project, and the partners fund 10 per cent. Fixed assets or existing stock can count as equity for a running business. For a new business, the equity share must be cash deposited in an account.
Security is the personal guarantee of all partners plus a corporate guarantee of the firm. Every partner is responsible for using and repaying the loan. There is no mark-up and no service charge, so the instalments repay only the principal.
For the Akhuwat loan, repayment is in equal monthly instalments over 36 to 60 months, according to the KP Directorate of Youth Affairs. Confirm your exact term with your branch, because the term can vary. If you miss an instalment, branch staff contact you personally to understand the problem. In genuine hardship the loan can be rescheduled, and community elders may help mediate. In extreme cases, such as death, permanent disability, or catastrophic loss, a loan may be written off as a charitable grant. That is a last resort, after community-led recovery efforts.
How do you check your application status?
There is no single status page for the whole programme, and the two routes work differently. For an Akhuwat loan, go back to the branch where you applied. Keep your CNIC and any application slip or reference number with you. Ask the loan officer which stage your application is at.
The stages are: application received, social and economic appraisal, guarantor check, approved, disbursed, and repaying. If documents or a guarantor are still pending, ask exactly what is missing and when to come back. Do not enter your CNIC on unofficial websites that claim to check your status. Akhuwat loan status is not shown on any third-party site.
For a Bank of Khyber loan, the portal is the application route, but the bank has not published a separate status-check process. Our source could not open the portal, so no status-check steps inside it can be confirmed here.
The KP Directorate of Youth Affairs publishes beneficiary lists under Downloads, then Ehsaas Naujawan Programme, on kpyouthaffairs.gov.pk. The latest lists seen were marked as on 30 April 2026. Those lists show who has already received a loan, not the live status of a new application.
What should you watch out for before you apply?
Three facts in this guide are unconfirmed, and you should know them before you apply. First, the Bank of Khyber has published no closing date for the programme. Any last date you see on a news or blog site is not from the bank, so treat it as unconfirmed. Second, the bank has published no processing time, so no one can honestly promise approval in a fixed number of weeks. Third, the bank has not published the number of Bank of Khyber loans made so far under the programme.
The confirmed numbers come from the Akhuwat side. By August 2026, Akhuwat had disbursed 9,927 loans worth Rs 1,936 million under the programme, with a near-100 per cent recovery record, according to the KP Directorate of Youth Affairs progress report. That figure covers Akhuwat loans only.
Watch out for fraud. No government department, bank, or Akhuwat charges a fee to approve a loan. Never pay an agent, and never share your CNIC, PIN, or OTP with anyone who calls or messages you. If someone asks for money to speed up your application, it is a scam.
Also be careful with old figures on other sites. Some guides still show application counts and approval rates from earlier cycles, and those numbers clash with each other.
Frequently asked questions
Is the Ehsaas Naujawan loan really interest-free?
Yes. The Bank of Khyber page says there is no mark-up or service charge, and it calls the loan a soft loan. Akhuwat also charges 0 per cent mark-up, so you repay only what you borrowed.
Can I apply alone for the Ehsaas Naujawan Programme?
No, not for the Bank of Khyber loan. That loan goes only to a registered firm, company, or partnership of 3 to 5 partners. If you want to apply alone, use the Akhuwat route, which lends Rs 100,000 to Rs 500,000 to a single borrower at a branch.
What is the age limit for the Ehsaas Naujawan Programme?
The age limit is 18 to 35 for both loan routes. Every partner in a Bank of Khyber firm must be in that range, and an Akhuwat borrower must be too. Each applicant must also be a permanent resident of Khyber Pakhtunkhwa with a valid CNIC.
How much can I borrow from the Bank of Khyber?
You can borrow Rs 1 million to Rs 5 million per firm, with no mark-up or service charge. The exact amount depends on the business potential and what the partners can show.
How much can I borrow from Akhuwat?
You can borrow Rs 100,000 to Rs 500,000. The loan is interest-free, and a guarantor stands behind it instead of property. You apply at your nearest Akhuwat branch in Khyber Pakhtunkhwa.
How long do I get to repay the Bank of Khyber loan?
You get up to 8 years, with a grace period of up to 20 months before equal monthly instalments start. Disbursement comes in tranches, after the required formalities are complete. The bank has published no processing time for the assessment itself.
Where do I apply for the Ehsaas Naujawan Programme?
For a Bank of Khyber loan, apply online at ehsaasnaujawan.bok.com.pk, the portal linked from the bank's scheme page. For an Akhuwat loan, apply at your nearest Akhuwat branch.
Can a government employee apply?
No. Employees of any government, semi-government, or autonomous body cannot take financing under the scheme, and the bank's FAQ repeats this rule. Bank of Khyber staff and consultants engaged on the scheme are also excluded, as are loan defaulters.
Is there a last date to apply?
No closing date has been published by the Bank of Khyber, as of 6 November 2026. Check the bank's own scheme page before you rely on any date shown elsewhere.
How do I check my Akhuwat loan status?
Go to the Akhuwat branch where you applied, with your CNIC and any application slip or reference number. Ask the loan officer which stage your application is at. Status is not shown on any third-party website.
Sources and official links
Check the destination address before entering personal information.
Related guides
PM Youth Business & Agriculture Loan: Before You Apply
Review the official eligibility rules, application route, and documents before starting.
Read guide
Prime Minister Youth Loan Scheme 2026: Complete Application, Eligibility & Tiers Guide
The Prime Minister Youth Loan Scheme 2026 provides subsidized business financing up to Rs 7.5 million for Pakistani citizens aged 21 to 45 across three tiers (0%, 5%, and 7% markup). Apply online through the official pmyp.gov.pk portal.
Read guide
Youth Loans & Financing Drive 2026: How to Apply, Eligibility & Loan Tiers
Master the Youth Loans & Financing Drive 2026 (PMYB&ALS). Learn Tier 1–3 loan limits (up to Rs 7.5M), 0% to 7% markup rates, NADRA CNIC portal steps, and eligibility rules.
Read guide
Punjab One Million Youth Skills Plan: Mahir, Global Rozgar, Advance Tech and Language Learning Explained
Punjab plans to train one million young people in technical and vocational skills over three years. The target was announced on 1 November 2026, and it covers industrial training, business process outsourcing, emerging technology, agriculture, and language learning. It is a target, not an open application form.
Read guide
CM Balochistan Youth Skills Scheme 2026 Online Apply & Registration Guide
Apply online for CM Balochistan Youth Skills Scheme 2026. Complete guide to B-TEVTA online registration, courses, monthly stipends, and 30,000 overseas jobs.
Read guide