This article explains public information. It does not determine eligibility or replace an official notice.
Quick Overview: How the Ehsaas Loan and Saving Wallet Differ
While both financial instruments were launched under Pakistan’s national poverty alleviation umbrella, they serve fundamentally different economic functions. One provides debt financing for business creation, whereas the other offers financial storage and digital inclusion for social cash transfers.
Understanding this operational distinction prevents low-income households from taking on unnecessary repayment burdens or missing out on enterprise capital.
What Is the Ehsaas Interest-Free Loan Programme?
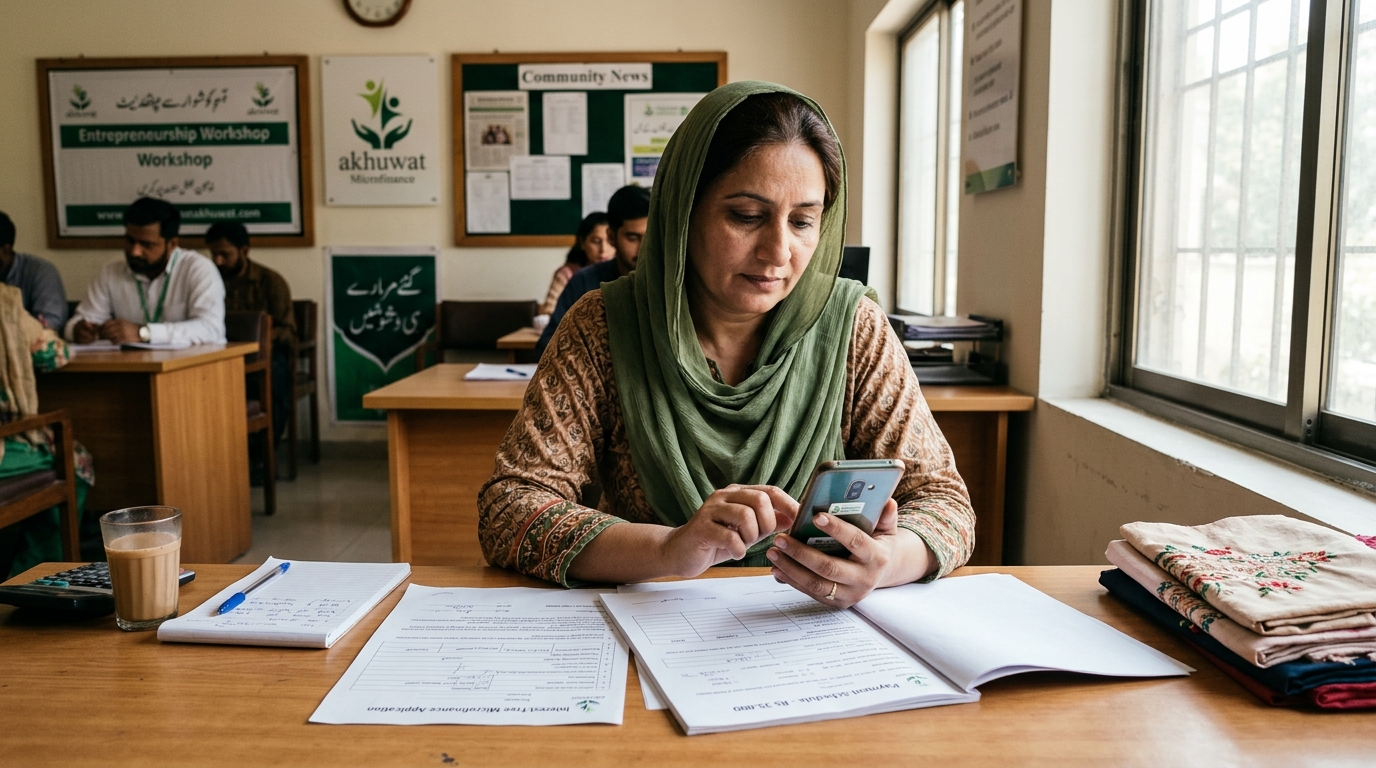
The Ehsaas Interest-Free Loan (IFL) initiative is a federal poverty graduation program implemented through the Pakistan Poverty Alleviation Fund (PPAF) in partnership with leading Islamic microfinance institutions, primarily Akhuwat Islamic Microfinance. It provides small interest-free business loans (Qarz-e-Hasna) ranging from Rs 20,000 to Rs 75,000 (with select agricultural and enterprise tranches extending up to Rs 100,000).
The program charges 0% interest and 0% administrative markup, requiring borrowers to repay only the exact principal amount over an agreed period of 12 to 24 months in equal monthly installments. Over 2.2 million interest-free loans have been disbursed across 110+ districts in Pakistan to support grocery shops, tailoring units, livestock rearing, embroidery centers, and street vending.
What Is the Ehsaas Saving Wallet (Bachat Account)?
The Ehsaas Saving Wallet (officially known as the Ehsaas Bachat Bank Account or BISP Digital Wallet) is a financial inclusion initiative developed in collaboration with partner commercial banks (such as Bank Alfalah and HBL Konnect). It converts traditional cash distribution into formal, digitized branchless banking for female beneficiaries of social welfare programs.
Unlike a loan, a saving wallet is not repayable debt; it is a fully functioning, zero-minimum-balance bank account registered under the female beneficiary’s own Computerized National Identity Card (CNIC). It allows beneficiaries to receive their quarterly Rs 13,500 Benazir Kafaalat stipends directly, retain savings in a secure digital vault, earn government incentive bonuses, pay household utility bills, and withdraw cash at biometrically secured ATMs whenever needed.
Side-by-Side Comparison Matrix: Loan vs. Saving Wallet
To determine which financial tool matches your immediate household needs, review the comparative breakdown below:
| Feature / Metric | Ehsaas Interest-Free Loan (IFL) | Ehsaas Saving Wallet (Bachat Account) |
|---|---|---|
| Primary Financial Function | Capital injection for enterprise creation / expansion | Secure digital repository for stipends and household savings |
| Capital / Benefit Amount | Rs 20,000 to Rs 75,000 (Up to Rs 100,000 in select sectors) | Holds quarterly grant (Rs 13,500) + voluntary personal deposits |
| Markup / Interest Rate | 0% Markup (Pure Qarz-e-Hasna) | 0% Interest (Islamic branchless digital account) |
| Repayment Requirement | Mandatory monthly installments over 12–24 months | None — Funds belong entirely to the beneficiary |
| Financial Risk Profile | Moderate (Debt obligation; failure to repay damages credit standing) | Zero Risk (Asset storage and savings protection) |
| Target Beneficiary | Men and women aged 18–60 capable of running a micro-enterprise | Female heads of households registered in BISP / Ehsaas Kafaalat |
| PMT Score Eligibility | Household PMT score between 0 and 40 | Household PMT score 32 or below (Kafaalat criteria) |
| Guarantor Requirement | Two local community guarantors required | No guarantors required |
| Application Method | In-person physical visit to nearest Akhuwat / PPAF branch | Automated enrollment via BISP Tehsil Office / partner bank desk |
| Key Partner Institutions | PPAF, Akhuwat Islamic Microfinance, NRSP, Kashf Foundation | BISP, State Bank of Pakistan, Bank Alfalah, HBL Konnect |
Who Should Apply for an Ehsaas Interest-Free Loan?
An interest-free loan is designed specifically for individuals who possess an entrepreneurial mindset, have an identifiable business skill, and require seed capital to purchase productive assets.
Ideal Scenarios for Micro-Enterprise Financing
Applying for an interest-free loan is the best financial decision under the following conditions: Starting a home-based business such as tailoring or embroidery requiring sewing machines; expanding a small neighborhood grocery shop (karyana) or fruit cart with wholesale inventory; livestock rearing in rural areas (goats, sheep, or dairy cattle); purchasing professional toolkits for electricians, plumbers, carpenters, or mechanics.
Eligibility Criteria, Guarantors & PMT Requirements
To qualify for an Ehsaas interest-free loan through Akhuwat or PPAF partner organizations, applicants must meet the following official benchmarks: Must be a Pakistani citizen aged 18 to 60 years holding an unexpired CNIC; household PMT score between 0 and 40 in the NSER registry; residence within a 5-kilometer radius of the local branch; provision of two reputable local community guarantors (non-family); and submission of a workable business plan.
How to Apply at an Authorized Akhuwat or PPAF Center
The application process for an interest-free loan is strictly physical; there is no online application form. Applicants must locate their nearest Akhuwat or PPAF branch, attend an initial interview with their original CNIC and utility bill, submit the application with guarantor details, undergo a residential social appraisal visit, and receive funds upon committee approval.
Who Should Choose an Ehsaas Saving Wallet?
The Ehsaas Saving Wallet is the superior choice for vulnerable households that do not have an active business, lack regular daily income to service monthly debt, or are primarily seeking to protect their welfare stipends.
Ideal Scenarios for Financial Protection & Savings
Opting for an Ehsaas Saving Wallet is ideal if you receive the quarterly Rs 13,500 Kafaalat grant and want to protect your money from unlawful agent deductions; eliminate hours waiting in crowded physical campsite lines; build emergency cash reserves in a PIN-protected account; and pay domestic utility bills directly from your mobile phone.
Features: Zero Balance, Biometric ATM Access & Mobile Transfers
The Ehsaas Saving Wallet provides modern branchless banking capabilities tailored for low-income citizens: Zero minimum balance with no penalty fees; biometric cash withdrawals at partner bank ATMs (HBL or Bank Alfalah) using thumbprint and CNIC; optional PayPak ATM debit card; and free interbank fund transfers for receiving family remittances.
How to Activate and Access Your Digital Wallet
Active Benazir Kafaalat recipients can activate their digital wallet by ensuring their mobile SIM is registered under their own CNIC, visiting the designated BISP banking booth or partner bank branch, completing biometric KYC verification, and receiving their account credentials via official SMS.
Decision Framework: 4 Questions to Ask Before Deciding
To avoid costly financial mistakes, ask yourself the following four diagnostic questions:
1. Do I have an active skill or business plan that generates immediate cash flow? If yes, an interest-free loan can multiply your income. If no, taking a loan creates unmanageable stress. 2. Can my household comfortably pay Rs 2,000 to Rs 5,000 each month in repayments? Even with 0% interest, principal must be repaid monthly. 3. Can I produce two reliable community guarantors? Without two non-family guarantors, microfinance loans cannot be approved. 4. Is my primary objective safety and digital cash management? If yes, the Ehsaas Saving Wallet is the exact tool designed for you.
Can a Household Benefit from Both Programmes Simultaneously?
Yes, absolutely. The Government of Pakistan and BISP explicitly permit and encourage eligible households to utilize both instruments in a complementary manner.
For example, a low-income family can have the female household head receive her quarterly Rs 13,500 Kafaalat cash transfer through her Ehsaas Saving Wallet, safeguarding welfare funds for food and education. Simultaneously, her husband or adult son (aged 18–60) can apply for an Ehsaas Interest-Free Loan through Akhuwat using his own CNIC to purchase a motorcycle rickshaw or open a roadside vegetable shop. This dual-track approach is the cornerstone of Pakistan’s poverty graduation strategy.
Public Safety Alert: Avoiding Fake Loan Apps and WhatsApp Processing Scams
Low-income citizens seeking interest-free loans or digital wallets are frequent targets of organized cybercrime syndicates. Protect your finances by adhering to these strict government safety rules:
No Online Loan Applications: Neither PPAF, BISP, nor Akhuwat offers instant online loans through downloadable Android APK apps, Facebook ads, or WhatsApp groups. Any app claiming to disburse 'instant Ehsaas loans' is an illegal scam. Never Pay Processing Fees: Official interest-free loans have zero processing fees, zero application charges, and zero file fees. Guard Your Mobile Banking OTPs: Never share your 4-digit ATM PIN or OTP with anyone. Report any extortion attempt to the BISP Helpline (0800-26477), Akhuwat (042-111-448-464), or the FIA Cybercrime Wing via 1991.
Frequently asked questions
What is the maximum amount available under the Ehsaas Interest-Free Loan?
The standard loan amount ranges between Rs 20,000 and Rs 75,000. In specific agricultural and enterprise development categories, loans up to Rs 100,000 may be granted based on business feasibility and repayment track record.
Is there any interest or markup charged on Ehsaas loans?
No. The Ehsaas Interest-Free Loan program operates strictly on the Islamic principle of Qarz-e-Hasna. Borrowers pay 0% interest, 0% markup, and zero hidden fees, repaying only the exact amount borrowed.
Can I apply for an Ehsaas interest-free loan online?
No. There is no official online application portal or mobile app for Ehsaas interest-free loans. All applicants must visit an authorized local branch of Akhuwat Islamic Microfinance or a PPAF partner organization in person.
Who is eligible to open an Ehsaas Saving Wallet?
Ehsaas Saving Wallets are designated for female beneficiaries of social welfare programs, primarily active recipients of the Benazir Kafaalat unconditional cash transfer scheme whose household PMT score is 32 or below.
Do I need to maintain a minimum bank balance in an Ehsaas Saving Wallet?
No. Ehsaas Saving Wallets feature a zero minimum balance requirement. Account holders are never penalized or charged maintenance fees, even if the account balance drops to zero.
Can men apply for an Ehsaas Interest-Free Loan?
Yes. Both men and women aged between 18 and 60 years who possess a valid CNIC, reside within the local branch radius, and have a workable business plan are eligible to apply for an interest-free loan.
What documents are required for an Ehsaas interest-free loan application?
Applicants must bring their original CNIC, copies of CNICs of two local community guarantors, a recent domestic electricity or gas utility bill, two passport-sized photographs, and a brief description of their proposed business enterprise.
Can I withdraw money from an Ehsaas Saving Wallet at any ATM?
Yes. Beneficiaries can withdraw cash at biometric ATMs operated by designated partner banks (such as Bank Alfalah and HBL) using their thumbprint and CNIC, or by using an authorized PayPak debit card at any 1Link ATM across Pakistan.
Does taking an Ehsaas loan disqualify my family from BISP Kafaalat stipends?
No. Microfinance loans taken through Akhuwat for legitimate small business creation do not automatically disqualify a household from BISP Kafaalat, provided the household’s overall socioeconomic PMT score remains within the eligible cutoff threshold.
How long does it take for an interest-free loan to be approved and disbursed?
The complete process—including application submission, field appraisal, community guarantor verification, and committee approval—typically takes between two to four weeks.
Sources and official links
Check the destination address before entering personal information.
Muhammad Salman specializes in Pakistani public sector financing, youth entrepreneurship schemes, and government subsidy programmes, cross-referencing all data against official SBP circulars and ministry directives.
Ayesha reviews programme-eligibility and payment content for accuracy against BISP, NADRA NSER, and provincial notices, and flags any guide that needs an update after an official policy change.
Related guides
Apni Chhat Apna Ghar Loan: Instant Qist Tracking
PITB portal par 15 lakh bila-sood loan ki approval check karne aur pehli qist (installment) track karne ka mukammal step-by-step tariqa.
Read guide
CM Balochistan Youth Skills Scheme 2026 Online Apply & Registration Guide
Apply online for CM Balochistan Youth Skills Scheme 2026. Complete guide to B-TEVTA online registration, courses, monthly stipends, and 30,000 overseas jobs.
Read guide
Fake 8171 SMS Check, Complaint & BISP Lottery Fraud Alert Guide
Spot fake 8171 SMS scams and report BISP lottery fraud. Step-by-step guide to reporting scammers on PTA 9000, BISP Helpline 0800-26477, Police 15, and FIA Cybercrime.
Read guide